


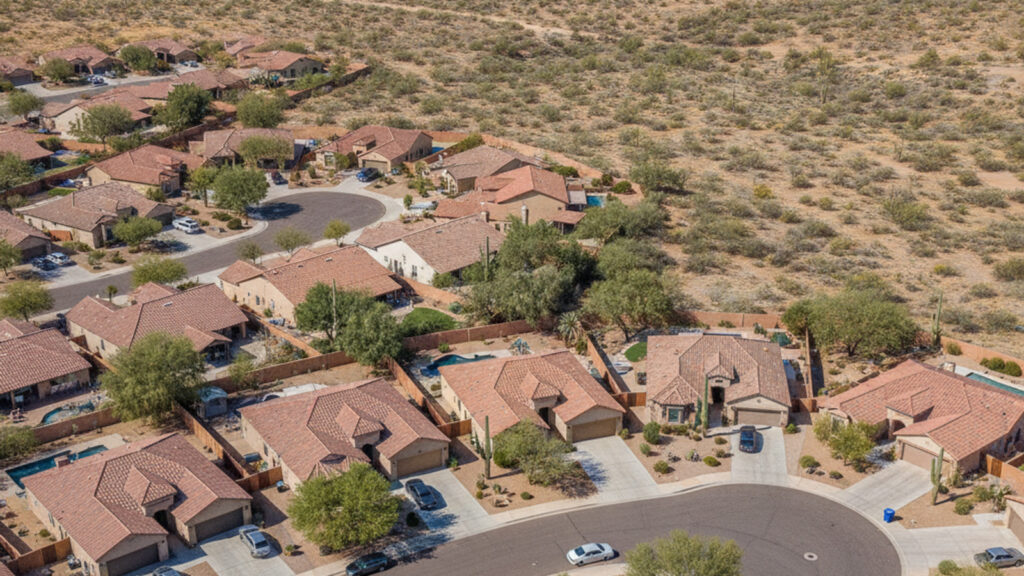
The median sale price for a home in Surprise, AZ sits around $435,000 as of mid-2026. Homes are staying on the market for roughly 78 days right now, which means you’re not being rushed into anything – you have time to actually run the numbers before you make an offer. This pacing is especially helpful for first-time home buyers in Surprise, AZ.
And you should run them. The sticker price is just the starting point. You’ll need to work in Maricopa County tax rates, homeowners insurance premiums, and whatever down payment you’re bringing to the table. Get those numbers wrong and you can end up house-rich and cash-poor inside of a year.
Calculating Your Home Buying Budget
Mortgage lenders are looking at two things when they size up your application: your gross monthly income and your existing debt. They want to know how much you make before taxes, then stack that against what you’re already paying on credit cards, car loans, and student debt.
That comparison produces your debt-to-income ratio, or DTI. It’s the number that tells a lender how much room you actually have for a mortgage payment. A lower DTI means more room – and that translates directly into a higher pre-approval amount.
The 28/36 Rule Explained
Most financial professionals work from the 28/36 rule, and it’s a decent gut check even before you talk to a lender. The idea is that no more than 28% of your gross monthly income should go toward housing-related expenses.
The second part of the rule covers your total debt picture: all your monthly debt payments combined – including the new mortgage – shouldn’t exceed 36% of your gross income. Lenders will pull that combined figure apart pretty carefully when they’re deciding whether to approve your loan.
Factoring in Local Property Taxes and Insurance
Your monthly payment is not just principal and interest. Maricopa County’s effective property tax rate runs roughly 0.44% to 0.47% of market value, which is actually lower than the national average – but it still adds up. On a median-valued home in the area, the annual tax bill comes in somewhere between $1,779 and $1,983.
Then there’s homeowners insurance. Arizona averages between $2,080 and $2,530 annually, which tacks on roughly $173 to $211 a month to your carrying costs. Both of those numbers belong in your budget from day one.
Surprise Home Prices and Down Payment Expectations
Recent sales data puts the median sale price in Surprise at roughly $435,000, with homes closing at about 98.5% of list price. Inventory sits at around 1,349 available homes, representing approximately 3.5 months of supply – enough selection that you shouldn’t feel like you’re fighting over the last seat on the bus.
Your down payment shapes everything downstream. It determines how much you borrow, what your monthly payment looks like, and whether you’re on the hook for private mortgage insurance. Twenty percent eliminates PMI entirely, but plenty of buyers get into homes with smaller amounts through conventional or FHA loans.
Current Market Trends in the West Valley
About 15.9% of homes in Surprise are selling above list price. The market is relatively stable overall, but well-priced properties in good condition still draw competitive offers – so don’t assume every house is a negotiation waiting to happen.
A listing that’s been sitting near that 78-day average is a different conversation than something that hit the MLS last week. Pay attention to days on market when you’re deciding what to offer.
Down Payment Assistance Programs in Arizona
There are real programs here worth knowing about. The Surprise Home Loan Assistance Program provides $5,000 to $10,000 depending on your Area Median Income. The Arizona Industrial Development Authority’s HOME Plus program pairs a 30-year fixed-rate mortgage with up to 5% in down payment assistance. The Maricopa County Home in Five Advantage program can provide qualified buyers up to 6% through an interest-free, forgivable second mortgage.
None of these are secrets, but a lot of buyers don’t ask about them until it’s too late to use them.
Hidden Costs of Buying in Maricopa County
Closing costs in Arizona typically run 2% to 5% of the purchase price. On a median-priced home in Surprise, that’s somewhere between roughly $4,700 and over $13,000 due on closing day – in addition to your down payment.
These fees cover the appraisal, title search, loan origination, deed recording, and a handful of other services. The money needs to be liquid and ready. Buyers who don’t set this aside early enough sometimes scramble at the finish line, which is not a comfortable position to be in.
Closing Costs in Arizona
Your lender is required to send you a Loan Estimate within three days of receiving your mortgage application. That document lays out your closing costs line by line, so there shouldn’t be any surprises if you read it carefully.
In a softer market you can sometimes negotiate seller concessions to offset some of these costs. With Surprise homes selling at 98.5% of list price, though, sellers aren’t always in a generous mood on that front. It’s worth asking – just don’t count on it.
HOA Fees and Routine Maintenance
A lot of neighborhoods in Surprise fall under a homeowners association, and dues vary considerably depending on what amenities the community offers. What doesn’t vary is how lenders treat those fees: they’re included in your DTI calculation, which means higher HOA dues lower the maximum loan amount you’ll qualify for.
Budget for maintenance too – especially your HVAC system, which doesn’t get a break during an Arizona summer. The standard guidance is setting aside 1% to 2% of the home’s value each year for upkeep. It sounds conservative until the air conditioner goes out in July.
How to Improve Your Purchasing Power
Your interest rate drives more of your monthly payment than almost anything else, and lenders reserve their sharpest rates for borrowers with strong credit and manageable debt. A half-percent drop in your rate can expand your total purchasing power by tens of thousands of dollars – so the months you spend cleaning up your financial picture before applying aren’t wasted.
Boosting Your Credit Score
Your credit score is the primary number lenders use to set your rate. Paying every bill on time and correcting any errors on your credit report will pull that score up over time – not overnight, but steadily.
Don’t open new credit cards or take out auto loans while you’re preparing to buy. New inquiries can temporarily drag your score down and create complications during underwriting.
Paying Down Debt and Getting Pre-Approved
Paying off existing debt reduces your DTI, which gives you room to qualify for a larger loan. Start with high-interest credit cards and personal loans – those free up the most budget space relative to the balance you eliminate.
Once your finances are in reasonable shape, get a pre-approval letter. It shows sellers you’re serious and financially capable, and it gives you a firm ceiling to work within when you’re searching.
Frequently Asked Questions
What salary do I need to qualify for a median-priced home in Surprise, AZ?
It depends on your current debt load and down payment. To comfortably afford a $435,000 median-priced home while following the 28/36 rule, buyers typically need a gross income that covers the mortgage, roughly $1,779 to $1,983 in annual property taxes, and around $2,080 to $2,530 in yearly insurance premiums.
How much do local property taxes and HOA fees in Surprise affect my total monthly affordability?
They directly reduce the amount you can borrow. Lenders must include Maricopa County property taxes and community HOA dues in your debt-to-income ratio, meaning higher fees will lower the maximum loan amount you qualify for.
Are there specific down payment assistance programs available for homebuyers in Surprise?
Yes. Options include the Surprise Home Loan Assistance Program offering $5,000 to $10,000, the HOME Plus program offering up to 5%, and the Home in Five Advantage program providing up to 6% in forgivable assistance.
Is it more affordable to buy a new construction or an existing home in the Surprise real estate market?
It depends on the specific property and builder incentives. Existing homes might carry a lower upfront purchase price, but new construction builders sometimes offer interest rate buydowns or cover a portion of the 2% to 5% Arizona closing costs.
If a lender pre-approves me for a certain amount, does that mean I can comfortably afford that much house in Surprise?
No. A pre-approval shows the maximum a lender is willing to let you borrow based on gross income – nothing more. Build your actual budget around your real take-home pay and what your day-to-day life costs, so the monthly payment stays comfortable once you’re living in the house.
Related Surprise Homebuyer Resources
Reviewed and updated: . This guide is educational and is not lending or financial advice. Rates, programs, fees and eligibility vary; consult a licensed lender and other qualified professionals. Learn more about Shannon Biszantz.